The phrase “legacy planning” can sound intimidating.
Trusts.
Tax strategies.
Beneficiary structures.
Estate documents.
Insurance.
Charitable vehicles.
Legal terminology.
For some families, sophisticated planning is absolutely appropriate.
But many retirees don’t need to begin with complexity.
They need to begin with clarity.
Who matters to you?
What do you want to accomplish?
What do you own?
And what would you like to happen to it?
Once those questions are answered, the appropriate planning tools become much easier to evaluate.
Legacy planning does not need to become a competition to create the most sophisticated estate.
Sometimes the strongest strategy is simply the one your family can understand and that accurately reflects your wishes.
Start With People, Not Products
One reason legacy planning becomes unnecessarily complicated is that people start with financial tools before defining their goals.
Should I create a trust?
Should I buy life insurance?
Should I gift money now?
Should I change my beneficiaries?
Those may all be legitimate questions.
But they come later.
First ask:
Who am I trying to help?
Maybe your priority is your spouse.
Perhaps you want assets divided equally among your children.
You might want to help grandchildren with education.
Maybe one family member needs more support than the others.
Or charitable giving may be important to you.
There is no universal definition of a meaningful legacy.
Once the people and priorities are clear, you can determine which tools actually serve those objectives.
Decide What You Want Your Money to Accomplish
Money can play several different roles in a legacy.
It can provide financial security for a surviving spouse.
Create an inheritance.
Support education.
Keep a family property.
Support a charitable organization.
Help an adult child through a difficult period.
Provide for a family member with special needs.
Or simply make settling your affairs easier.
Different objectives can require different planning.
This is why a vague goal such as “I want to leave something behind” is less useful than a specific one.
What does “something” mean?
For whom?
And why?
The clearer you are, the simpler the planning conversation often becomes.
Remember That Your Retirement Comes First
Legacy planning can become emotionally complicated because many retirees feel a strong responsibility to preserve assets for their children.
That can sometimes lead people to hesitate to spend money on themselves.
But retirement assets have an important first job:
Supporting your retirement.
You may need income for decades.
Healthcare needs can change.
Homes need repairs.
Inflation can increase expenses.
Travel, hobbies, and family experiences may be important to you.
A good legacy plan should not leave you afraid to use the money you worked decades to accumulate.
That does not mean inheritance goals are unimportant.
It means they should be balanced against your own financial security.
We generally believe it is more useful to create a retirement plan that supports your life first and then determine how legacy goals fit within that structure.
Keep Beneficiary Planning Straightforward
For many retirees, one of the simplest legacy-planning steps is reviewing beneficiaries.
Start with accounts that permit beneficiary designations, such as retirement accounts and life insurance policies.
Who is currently named?
Are there contingent beneficiaries?
Do those choices still reflect your intentions?
Have any beneficiaries died?
Have family relationships changed?
Then compare these decisions with your broader estate plan.
A simple beneficiary review may uncover issues long before more complicated strategies need to be considered.
Organize What You Already Have
Legacy planning can become difficult for families simply because they do not know what exists.
Consider creating an organized inventory of important financial information.
That may include:
Banking relationships.
Investment and retirement accounts.
Insurance policies.
Real estate.
Estate documents.
Tax contacts.
Financial advisors.
Outstanding debts.
Regular household obligations.
Digital assets or accounts.
The goal is not to place sensitive information somewhere insecure.
The goal is to make sure the appropriate people can determine what exists and where to obtain the necessary information.
Sometimes organization accomplishes more for a family than adding another complicated financial tool.
Decide Who Should Be Responsible
Every legacy plan involves people who may eventually need to act.
An executor or personal representative may administer an estate.
A trustee may oversee trust assets.
An agent under a power of attorney may manage financial matters.
Someone may be designated to make healthcare decisions.
These roles require more than affection.
They require responsibility.
Before naming someone, consider whether that individual is:
Trustworthy.
Organized.
Able to communicate with family members.
Comfortable handling administrative responsibilities.
Available to serve.
And willing to accept the role.
It can also be valuable to name appropriate backups when possible.
A simple plan with the right people can be more effective than a sophisticated plan involving people who are unable or unwilling to carry it out.
Consider Whether Lifetime Giving Fits Your Goals
Not every legacy needs to wait until death.
Some retirees enjoy helping family while they are alive.
You may be able to watch a grandchild benefit from education assistance.
Help an adult child purchase a first home.
Support a charitable organization whose work you value.
Or provide assistance when it is needed most.
For 2026, the federal annual gift-tax exclusion is $19,000 per recipient for qualifying gifts. Married couples potentially have separate annual exclusions available under applicable rules.
But tax limits should never be the only consideration.
Before making significant gifts, ask whether you can comfortably afford them while preserving enough flexibility for your own retirement.
Lifetime gifting should fit the retirement plan—not weaken it.
Don’t Create Complexity Without a Reason
Trusts and other advanced estate-planning strategies can be very useful when circumstances call for them.
Blended families.
Minor beneficiaries.
Special-needs planning.
Business ownership.
Privacy objectives.
Asset-management concerns.
Large or complicated estates.
Certain tax strategies.
Those situations may warrant more sophisticated legal planning.
But complexity should solve a problem.
It should not exist simply because complexity sounds more comprehensive.
If a straightforward estate plan accomplishes your objectives, adding layers of unnecessary structures can sometimes increase costs, administration, and confusion.
A qualified estate-planning attorney can help determine which legal tools are appropriate for your situation.
Communicate Enough to Reduce Surprises
Families do not necessarily need to know every detail of your finances.
But complete secrecy can create its own problems.
If appropriate, consider communicating the broad intentions behind your plan.
Who should your family contact?
Where are documents stored?
Who has been assigned important roles?
Are there particular personal wishes family members should understand?
Do adult children have expectations that differ significantly from your actual plan?
Legacy conversations can be uncomfortable, particularly when different beneficiaries will receive different amounts.
But thoughtful communication can sometimes prevent misunderstandings later.
The goal is not to justify every financial decision.
It is to reduce avoidable confusion.
Review the Plan as Life Changes
Simple does not mean permanent.
Even a straightforward legacy plan deserves regular attention.
Family situations evolve.
Assets change.
Tax laws change.
Health changes.
Relationships change.
Priorities change.
A legacy plan should therefore have enough flexibility to evolve with your life.
Reviewing the plan periodically can help ensure yesterday’s decisions still represent today’s intentions.
Don’t Let Estate-Tax Headlines Create Unnecessary Complexity
Tax planning is important, but not every household needs an elaborate federal estate-tax strategy.
For 2026, the federal basic estate and gift tax exclusion is $15 million per individual.
The federal annual gift-tax exclusion is $19,000 per recipient.
Those figures may mean federal estate tax is not the central legacy issue for many families, although state taxes and individual circumstances can differ.
For a large number of retirees, the more immediate questions are much more practical:
Are beneficiaries correct?
Can a spouse manage the finances?
Are important documents current?
Does someone have authority if I become incapacitated?
Does my family know who to contact?
Do my assets and estate documents tell the same story?
Clarity on those issues can be extraordinarily valuable.
A Legacy Should Reflect the Life You Built
Legacy planning is sometimes presented as simply maximizing the amount transferred to the next generation.
But that is only one possible goal.
Your legacy may also include the experiences you share with your family during retirement.
The causes you support.
The help you provide while alive.
The financial confidence you give a surviving spouse.
The values you communicate to children and grandchildren.
And the simplicity you create for the people who eventually manage your affairs.
A strong legacy is not necessarily the most complicated.
It is one that reflects what mattered to you.
Simplifying Legacy Planning Through the HFP S.T.A.R. Strategy
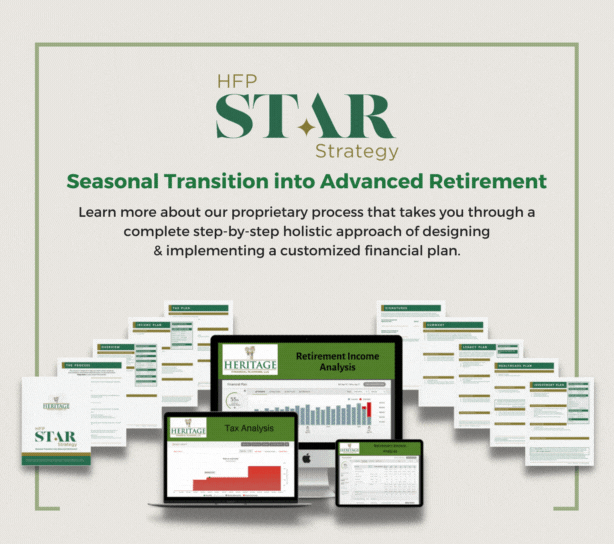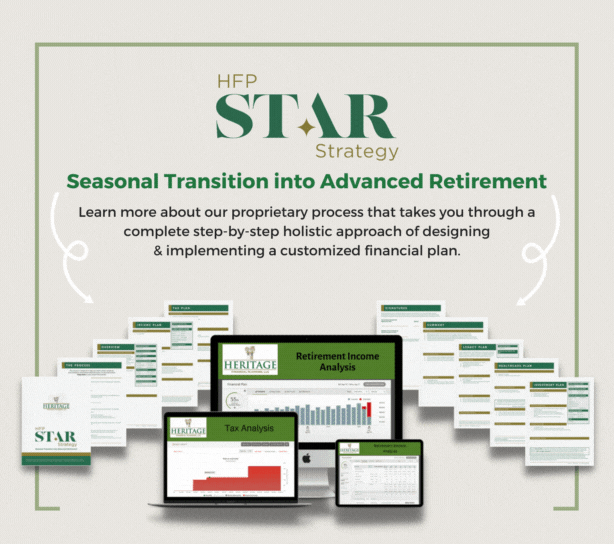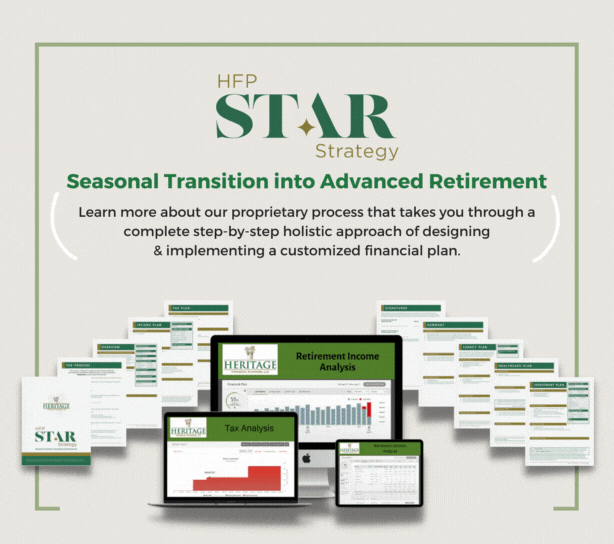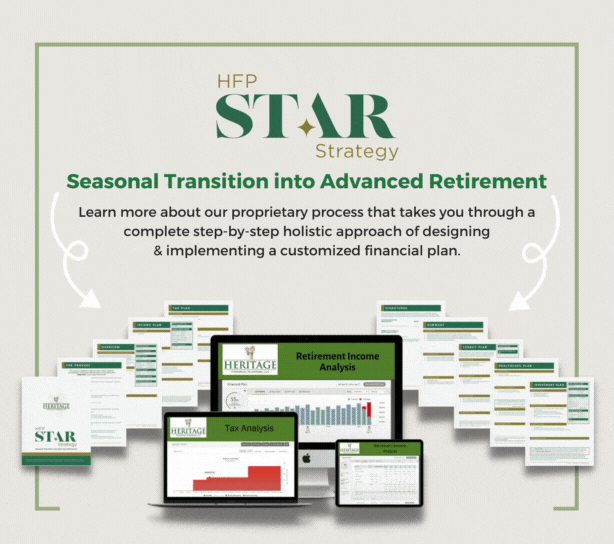
At Heritage Financial Planning, our proprietary HFP S.T.A.R. Strategy—Seasonal Transition into Advanced Retirement is designed to create a well-rounded, step-by-step retirement strategy.
It coordinates five essential areas:
Income Planning
Age-Appropriate Investment Strategies
Tax Planning and Positioning
Healthcare Strategies
Legacy Planning
Legacy planning belongs within this process because the assets you eventually leave behind are directly connected to the financial decisions you make throughout retirement.
Our goal is to help clients clarify what they want their financial resources to accomplish, evaluate how their accounts and beneficiaries fit together, and identify financial questions that may need coordination with an estate-planning attorney or tax professional.
You do not necessarily need the most complicated plan.
You need a plan that makes sense for your family, protects your retirement priorities, and clearly reflects what you want to accomplish.
If you’d like to bring more clarity and organization to your retirement and legacy planning, contact Heritage Financial Planning to schedule an appointment. Through our HFP S.T.A.R. Strategy, we can help you connect today’s retirement decisions with the people and priorities you want your financial life to support tomorrow.
Click here to learn more about our HFP STAR Strategy process.
Sources:
1 . Internal Revenue Service — Frequently Asked Questions on Gift Taxes – https://www.irs.gov/businesses/small-businesses-self-employed/frequently-asked-questions-on-gift-taxes
2 . Internal Revenue Service — Estate and Gift Tax: What’s New – https://www.irs.gov/businesses/small-businesses-self-employed/whats-new-estate-and-gift-tax
3 . Heritage Financial Planning — HFP S.T.A.R. Strategy – https://heritagefinancialplanning.net/about/heritage-financial-star-strategy/